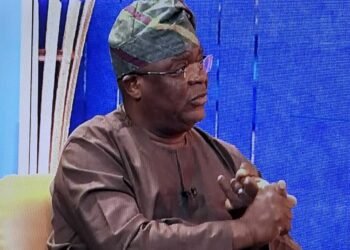
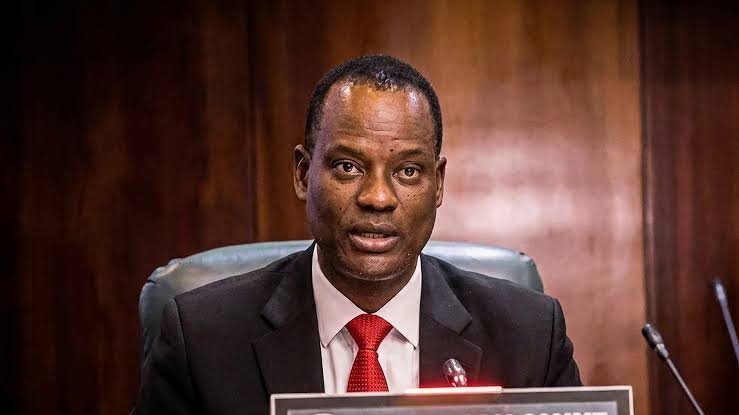
Nigeria’s Minister of Finance and Coordinating Minister of the Economy, Taiwo Oyedele, has said high financing costs, currency risks and limited access to affordable long-term capital are constraining Africa’s ability to fund critical infrastructure and expand energy access.
Oyedele made the remarks while speaking at the United Nations Dialogue on Solutions to Climate Finance in New York, on the sidelines of the 81st session of the United Nations General Assembly.
The minister said Africa’s development ambitions, particularly in the energy sector, require substantially greater access to affordable and long-term financing.
He argued that African countries face additional financing burdens despite the continent’s relatively low contribution to global carbon emissions.
Oyedele described some of those additional costs as a “prejudice premium” and “narrative cost”, while identifying currency risk and what he called a “stereotype tax” as further obstacles to mobilising capital for energy and other infrastructure projects.
The minister called for a shift in the global approach to climate finance, including simpler access to affordable capital for developing countries and financing arrangements that better reflect their economic and development circumstances.
He also urged increased investment in gas and other transition energy sources in Africa, arguing that the continent needs more reliable and affordable energy while pursuing a transition towards cleaner sources.
Oyedele said greater investment in Africa’s energy sector could also diversify global energy supplies and reduce concentration risks, particularly amid disruptions affecting the Gulf region.
The minister stressed that Africa’s energy transition must take account of the continent’s significant energy-access deficit.
He said the transition should therefore be accompanied by investment that allows African countries to expand energy supply and meet development needs while gradually moving towards cleaner energy sources.
For Nigeria, Oyedele said the immediate priority was to implement policies and programmes aimed at reducing poverty, expanding economic opportunities and accelerating the distribution of shared prosperity.
He said achieving those objectives would require stronger international cooperation and a financing framework capable of helping developing countries mobilise the capital required for infrastructure investment.
Oyedele’s intervention places the cost and structure of development finance at the centre of Africa’s infrastructure and energy debate, while linking climate-finance discussions to the continent’s immediate need for electricity and broader economic development.
His call comes amid wider international efforts to improve financing frameworks for developing economies and better assess the debt risks facing low-income countries.